Bitcoin Funding Turns Negative While $45.3B OI Jumps 8.3% in 24h
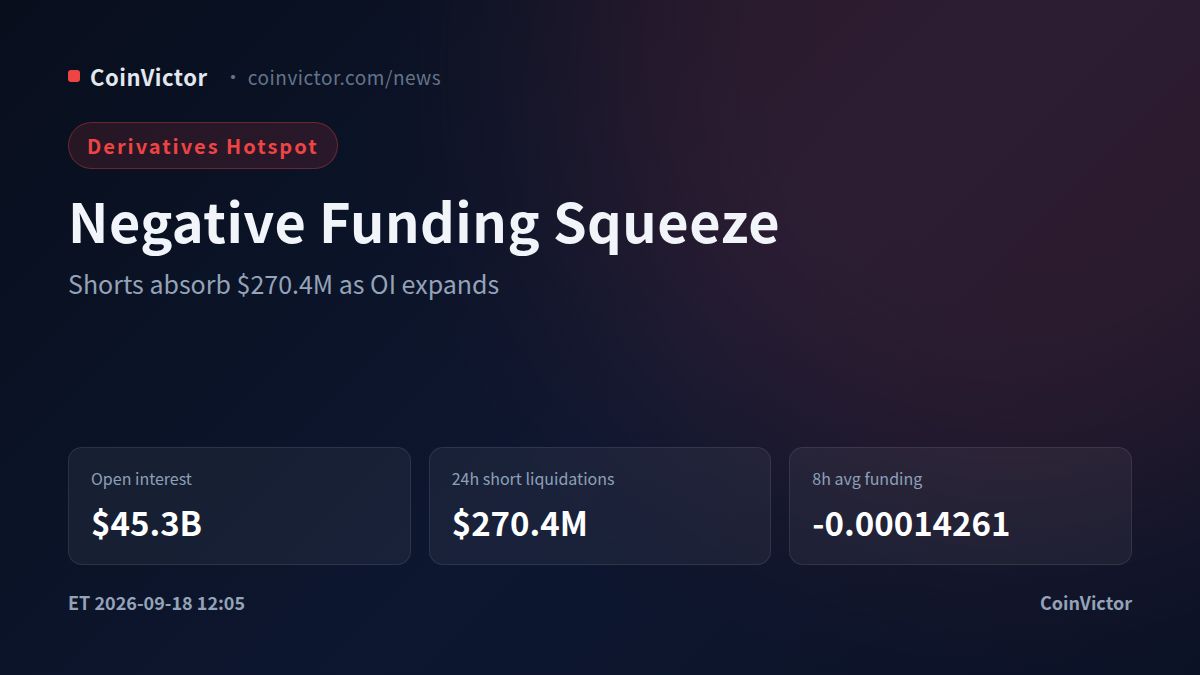
Bitcoin derivatives are flashing a crowded-short signal rather than a clean bearish one: price is $80,719, total open interest is about $45.3B, and aggregate OI has risen 8.3% in 24 hours. At the same time, the 8-hour average funding rate is negative at -0.00014261 in the source decimal format. That combination means leverage is building while shorts are still receiving funding on average, leaving the market exposed to another squeeze if price holds firm.
News context: Google News coverage portrays Bitcoin as resilient despite macro pressure, while broader crypto coverage continues to focus on the market’s expanding wealth and participation.
OI growth is concentrated but broad
The exchange breakdown shows that this is not a single-venue anomaly. Binance holds the largest share at 19.5%, with OI up 6.3% over 24 hours and 5.3% over four hours. Gate follows with 11.9% of aggregate OI after an 8.4% daily increase, while Bybit represents 10.5% and has gained 9.6%. Bitget adds 6.0% and is up 6.9% over the same period. OKX has a smaller 5.3% share but the fastest expansion among the leading venues at 9.5% in 24 hours.
The important distinction is that OI is rising faster than the market is de-risking. The total has climbed to $45.3B even as one-hour OI is slightly lower by 0.2%, suggesting some immediate cooling but no meaningful unwind of the larger leverage build. For a negative-funding setup, that leaves plenty of short exposure available to fuel another upside move if resistance breaks.
Funding is negative only in pockets
Funding is uneven across venues. CoinEx is the clear downside outlier at -0.4%, while Bitunix and Kraken are also negative after rounding to one decimal place. By contrast, Binance, OKX, Bybit, BitMEX and WhiteBIT are positive at 0.0% when rounded to one decimal, with OKX and Bybit both near the upper end of the displayed major-venue range. The cross-exchange spread matters: the market-wide average is negative, but the largest pools of open interest are not uniformly paying shorts to stay positioned.
This weakens the case for treating negative funding as a universal bearish confirmation. Instead, it points to fragmented positioning, with the most aggressive short bias concentrated on selected platforms. If those shorts remain open while price stays above $80,000, funding can remain negative even as liquidation risk shifts upward.
Liquidations confirm a short squeeze
The liquidation profile is decisively one-sided. Over 24 hours, short liquidations reached $270.4M against only $6.6M of long liquidations. The imbalance was even sharper over four hours, with $199.0M in shorts liquidated versus $3.0M in longs. In the latest one-hour window, shorts still led at $4.9M compared with $1.1M for longs.
The largest individual events reinforce the pattern. A Hyperliquid short liquidation worth $8.5M occurred near $78,197, followed by another worth $5.9M near $80,409. These levels show that upward price movement has already been forcing short risk out of the market, rather than triggering broad long capitulation.
Positioning remains internally split
The long/short ratio data adds an important caveat. Across the reported account set, longs are 50.7% and shorts 49.3%, while active takers are almost balanced at 50.5% long. Yet Binance accounts are 49.3% long, while Binance takers are only 42.9% long, showing that aggressive flow is more short-biased there. Gate shows the reverse: 43.5% of accounts are long, but takers are 51.4% long. Bybit accounts are 53.5% long, adding another layer of passive long exposure.
Verdict: The near-term bias is squeeze-prone while Bitcoin holds $80,409 and OI remains near $45.3B; a move through $80,719 with funding still negative would favor further short covering, while a break below $78,197 would invalidate the squeeze view and confirm that leverage is finally unwinding. Data as of 00:05 Beijing time on Sep 19, covering Binance, OKX, Bybit and other major venues.