Bitcoin Funding Turns Negative While $44.5B OI Builds 3.1% More
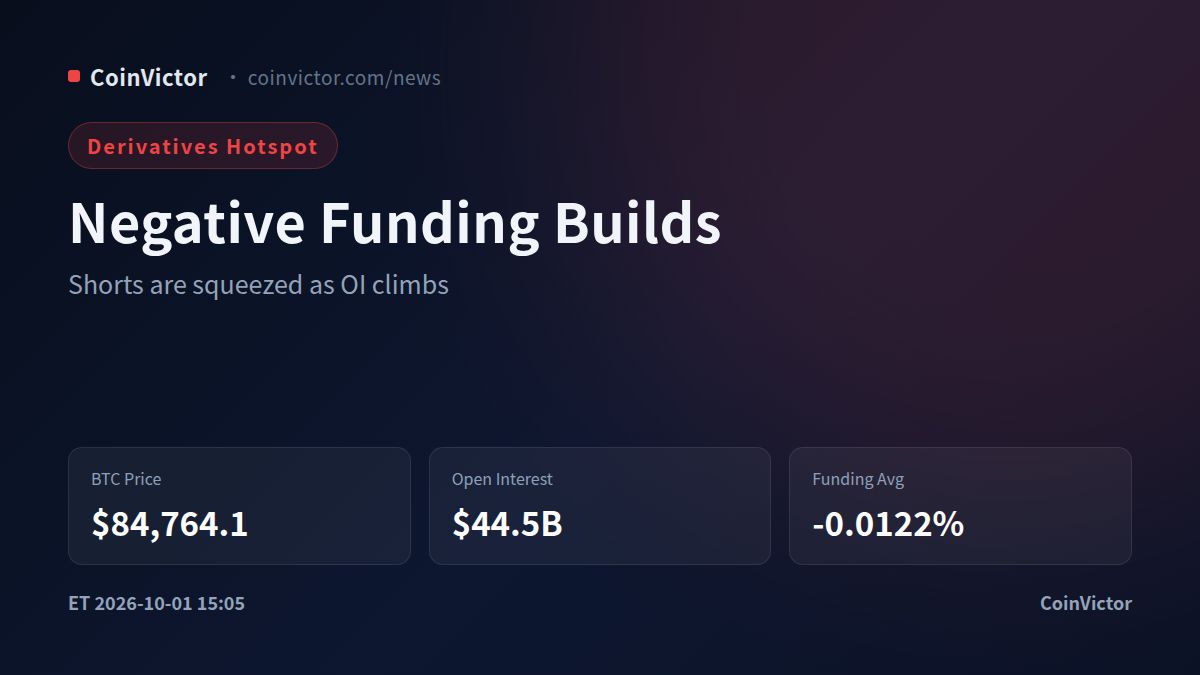
Bitcoin derivatives are sending a conflicted signal: the average 8-hour funding rate is negative at -0.0122%, yet total open interest stands at $44.5B after rising 3.1% in 24 hours. With spot at $84,764.1, the market is adding leverage while shorts, rather than longs, are absorbing most realized liquidation pressure.
A softer-than-expected US PCE reading has reduced near-term expectations for an October rate hike, giving risk assets some room. In crypto derivatives, however, the more important question is whether negative funding reflects healthy short hedging or a crowded bearish trade vulnerable to another squeeze.
OI is expanding across the major books
Binance remains the largest tracked venue with $8.3B of BTC OI and an 18.6% share, up 4.1% over 24 hours. Bybit holds $4.8B, or 10.8%, after a 5.7% increase, while Gate carries $4.5B and a 10.1% share following a 5.3% rise. OKX is smaller at $2.5B, representing 5.5%, but its 6.1% daily increase is the fastest among these leading venues.
The cross-venue pattern matters. Binance added 2.0% over four hours, OKX gained 2.9%, Bybit rose 1.7%, and Gate increased 1.7%. Bitget was the exception: its $2.7B OI was up 2.2% over 24 hours but down 3.2% over four hours. This is not broad deleveraging; it is a redistribution and expansion of exposure, which can intensify any move through crowded liquidation zones.
Funding is negative in pockets, not everywhere
The headline negative average masks a fragmented funding map. The strongest positive readings are BitMEX at 0.010%, Bybit at 0.010%, Bitfinex at 0.011%, and Bitget at 0.010%. Binance is also positive at 0.009%, while OKX is milder at 0.003%. Against that, CoinEx is sharply negative at -0.375%, WhiteBIT is -0.012%, Bitunix is -0.008%, and Gate is -0.001%.
That dispersion suggests the bearish carry is concentrated rather than universal. Traders paying negative funding are effectively compensating longs on those venues, but the positive rates on the largest books show that leverage is not uniformly short. The market can therefore sustain a negative aggregate reading without producing an immediate collapse, especially while OI continues to build.
Liquidations favor a short squeeze
The liquidation structure is decisively asymmetric. Over 24 hours, short liquidations reached $26.8M versus $15.0M for longs, out of a $41.7M total. The same pattern appears over 12 hours, with $22.7M of shorts liquidated against $11.1M of longs. Over four hours, shorts lost $18.7M while longs lost $1.0M; in the latest hour, the split was $4.6M against shorts and $0.2M against longs.
The largest recorded event was a $1.7M Binance short liquidation at $85,309.5. Other notable short liquidations occurred at $84,736.3 and $84,662.8, while a $0.8M OKX long liquidation appeared at $83,270.9. The long/short ratio also shows a split personality: account positioning is long overall at 54.5%, but taker flow is short at 50.6% across the available venues. Binance takers were 52.8% short, and Gate takers were 51.7% short, even as account longs dominated on Bybit at 56.0% and Bitget at 58.7%.
Verdict
The near-term bias is squeeze-positive but not fully bullish: negative funding, rising $44.5B OI, and short-heavy taker flow favor another test of $85,309.5. A sustained move above that liquidation level would pressure remaining shorts; failure to hold $84,561, followed by a break toward the $83,270.9 long-liquidation zone, would invalidate the squeeze view and confirm that expanding OI is bearish inventory instead. Data as of 03:05 Beijing time on Oct 2, covering Binance, OKX, Bybit and other major venues.