BNB Derivatives: 8.0% Annualized Basis Meets $1.12B Open Interest
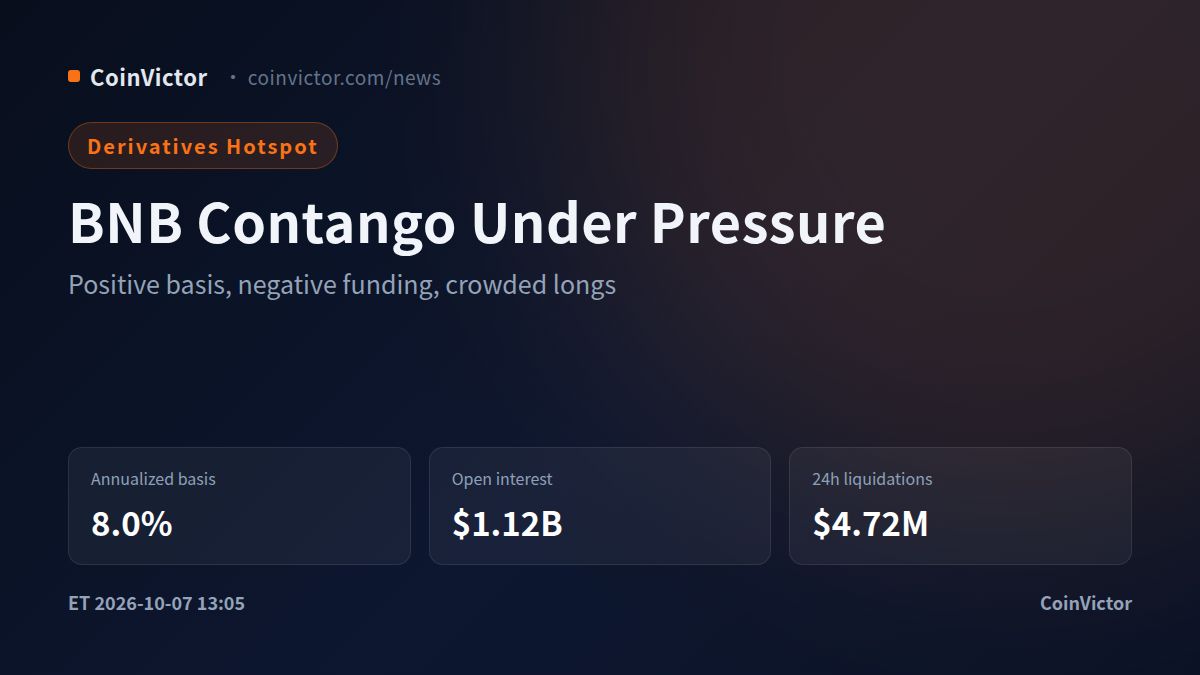
The BNB derivatives market is showing a sharp internal split: the basis is positive at 0.0%, equivalent to an 8.0% annualized premium, yet the average funding rate is -0.0%. With price at $772.34 and total open interest at $1.12B, this is contango without clear evidence that leveraged longs are being rewarded.
Market context is also being shaped by reports that U.S. authorities moved crypto assets including BNB, although no confirmed sale was established in the supplied coverage.
Open interest is contracting at the leaders
Position concentration makes the retreat meaningful. Binance holds $445.6M, or 39.9% of tracked BNB open interest, after a 3.6% decline over the past day. Gate follows with $197.6M and a 17.7% share, down 2.2%, while Bybit carries $113.3M, or 10.1%, after a 3.9% drop. Bitget contributes $68.3M and 6.1%, with a smaller 1.9% decline.
The combined picture is not a broad expansion of risk: tracked open interest fell 2.7% in twenty-four hours, even as it edged up 0.3% over the latest hour. Binance and Bitget both added 0.4% and 0.3% respectively over four hours, but Gate fell 2.5% and Bybit slipped 0.1%. That contrast suggests short-lived rebuilding on selected venues rather than a synchronized return of leverage.
Funding dispersion weakens the contango signal
Funding is uneven enough to challenge a simple bullish interpretation of the positive basis. Bitget and Gate both show 0.0% current funding when rounded to one decimal place, while Coinbase is also 0.0%. The most negative readings are CoinEx at -0.8%, KuCoin at -0.0%, WhiteBIT at -0.0% and OKX at -0.0%. Bybit, Binance and several other major venues are at 0.0%.
At the other end, BitMEX is 0.0%, Paradex is 0.0% and Lighter is 0.0% after rounding. The raw cross-venue spread still matters: traders are paying to hold some long exposure on selected books while receiving funding on others. Combined with the negative aggregate average, the premium in futures looks more like a fragmented pricing effect than a clean directional bid.
Long positioning meets long-side liquidation
Account positioning remains heavily long. Binance accounts are 69.7% long, OKX accounts 71.3% long, Bybit accounts 73.4% long and Gate accounts 65.3% long. Active taker flow is less optimistic: Binance takers are 66.1% long, while Gate takers are only 55.8% long. This account-versus-execution gap indicates that many traders still hold long exposure even as incoming market activity is closer to balanced.
The liquidation structure reinforces that risk. Over twenty-four hours, long liquidations reached $4.70M against only $18.7K in shorts. The twelve-hour window recorded $399.6K in long liquidations versus $14.1K in shorts, while the latest hour was unusual in the opposite direction: $163.0K in shorts versus $7.68 in longs. The largest reported long liquidation levels were $756.64 and $757.09, with losses of $613.5K and $388.8K respectively. Those prints show where crowded leverage has already been flushed, not proof that downside pressure is finished.
Verdict
BNB contango is currently a fragile premium, not a strong bullish confirmation. The key downside level is $756.64; a break there alongside open interest holding above $1.12B would signal that leverage is absorbing weakness and could extend the long squeeze. The bearish-contango view would be invalidated if BNB reclaims $772.34 while open interest rises above $1.12B and the aggregate funding average turns positive rather than remaining -0.0%. Data as of 01:05 Beijing time on Oct 8, covering Binance, OKX, Bybit and other major venues.