Derivatives Daily: $112.8B OI and $198.6M Liquidations on Nov 7
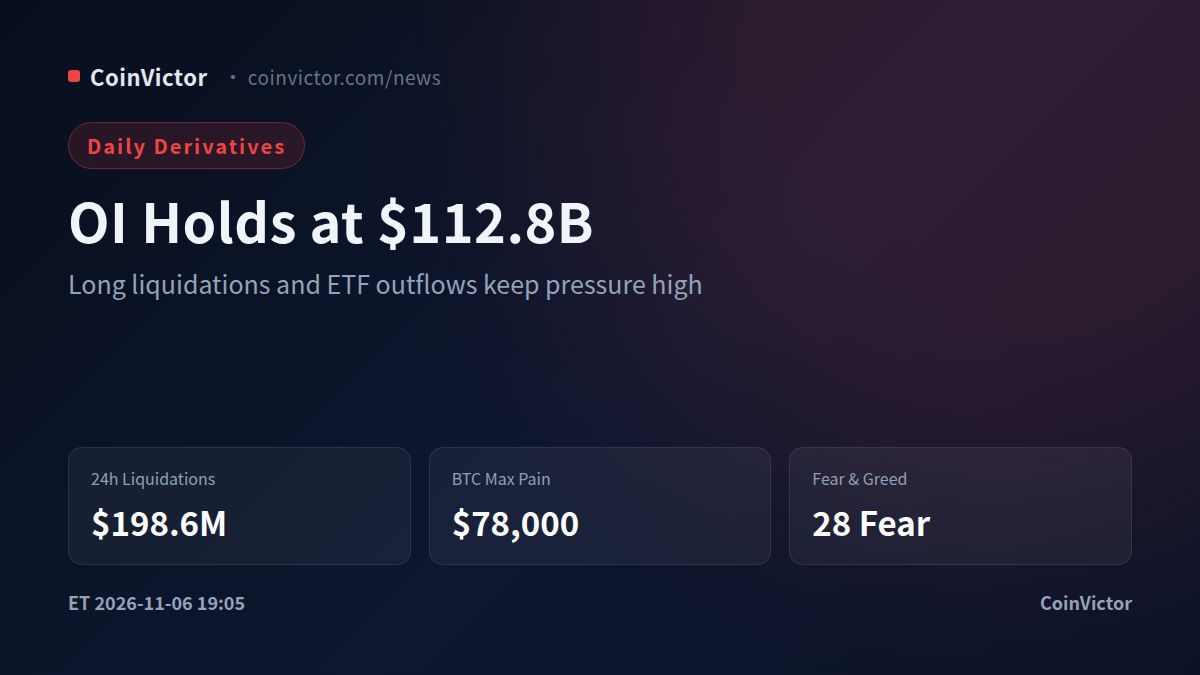
The derivatives market is carrying $112.8B in total open interest, but the latest reset has been painful for longs: 24-hour liquidations totaled $198.6M, including $125.2M in long positions versus $73.4M in shorts. With Bitcoin around $75,749 in the options snapshot and the Fear and Greed Index at 28, the tape still reflects defensive positioning rather than a clean risk-on rebound.
Longs absorbed the liquidation wave
The liquidation structure is decisively long-heavy. Across the latest 24-hour overview, long liquidations reached $125.2M while shorts accounted for $70.5M, for a combined $195.7M and 64,905 events. The broader derivatives feed reports a similar $198.6M total, confirming that forced selling, rather than a short squeeze, dominated the session.
Bitcoin was the largest source of stress among the leading coins, with $75.0M liquidated: $57.5M from longs and $17.5M from shorts across 6,930 events. Ethereum followed with $43.0M, including $32.3M in long liquidations. ZEC was different, posting $17.3M total with $13.3M from shorts, while AKE recorded $9.7M and XRP $9.2M. This split suggests that the market-wide pressure was concentrated in major-coin longs, while selected altcoins also punished crowded shorts.
ETF demand has not confirmed a rebound
Spot ETF flows add another bearish layer. Bitcoin recorded a flat flow on Nov. 6, leaving its seven-day total at negative $1,495.8M. The sequence was uneven: a $17.2M inflow on Oct. 29 was followed by outflows of $643.2M, $398.6M and $115.6M, then a $74.6M inflow, a $430.2M outflow and finally zero. Bitcoin ETF cumulative net flow remains $56,162.3M, while reported assets under management are $98,821.5M.
Ethereum’s latest available reading, dated Nov. 5, showed a $99.9M outflow. Its seven-day total was negative $554.5M, despite a $53.0M inflow on Nov. 4. The other reported days were all outflows, including $21.4M, $105.5M, $155.7M, $139.7M and $85.3M. The ETF data therefore offers little evidence that institutional demand is absorbing the current derivatives deleveraging.
Options define a narrow recovery map
Bitcoin options open interest is $26.4B, with a put-to-call open-interest ratio of 0.6926. The aggregate max pain for the Nov. 13 expiry is $78,000, above the $75,748.96 index price. Near-term expiries show a descending path: $77,500 for Nov. 7, $76,500 for Nov. 8, $76,000 for Nov. 9 and $75,500 for Nov. 10. The Nov. 13 level is the first meaningful upside magnet, but the call-heavy structure at that expiry also leaves room for resistance around $78,000.
Verdict: The immediate bias is cautiously bearish-to-neutral while Bitcoin remains below $78,000 and total market OI stays near $112.8B. A sustained reclaim of $78,000 with OI expanding from $112.8B would invalidate the downside view and signal healthier demand; a loss of the $75,500-$75,000 options zone while long liquidations remain dominant would reinforce continuation risk. Data as of 08:05 Beijing time on Nov 7, covering Binance, OKX, Bybit and other major venues.