Shiba Inu OI Hits $50.9M as Long Liquidations Reach $243.6K
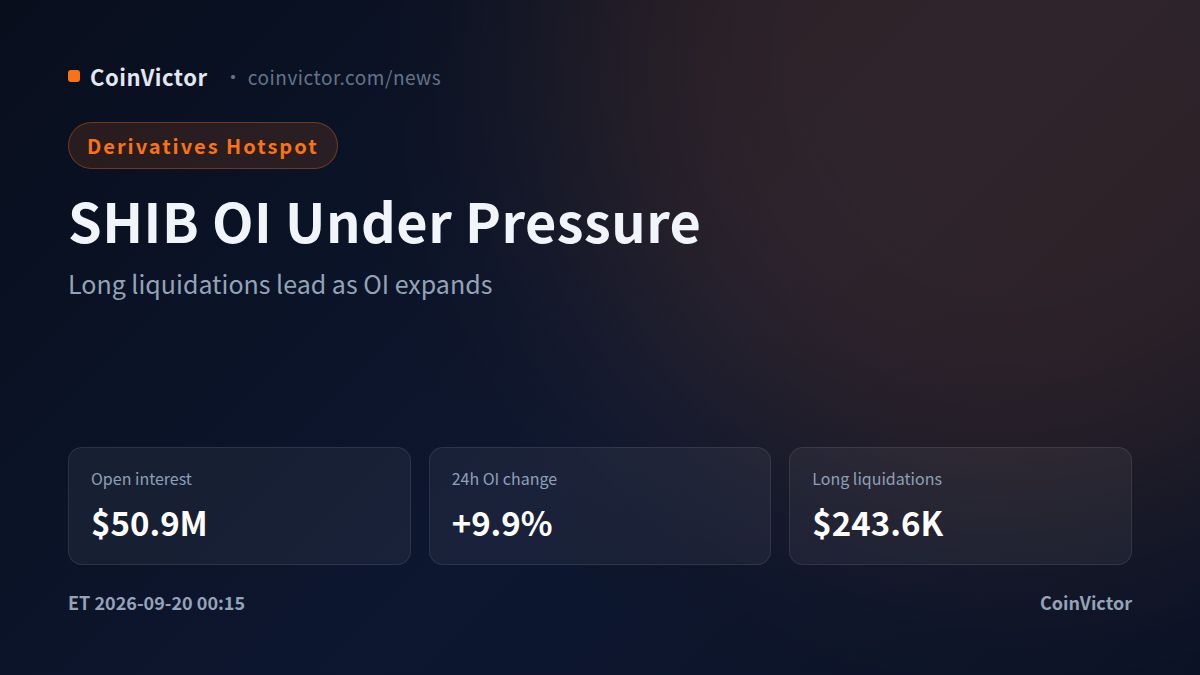
Shiba Inu futures open interest climbed 9.9% in 24 hours to $50.9M even as SHIB fell 2.0% to $0.00000537, creating a clear price-OI tension: leverage is being added into weakness rather than removed. The market is therefore not showing a clean bullish breakout yet; it is showing a larger positioning base that is increasingly vulnerable to a directional move.
Recent commentary has focused on a large token addition, a resistance test and a possible technical recovery, but the derivatives data points more directly to positioning risk than to confirmation of a trend reversal.
Bitget leads, but OI growth is uneven
The exchange distribution shows a concentrated but not dominant structure. Bitget holds the largest reported share at 20.1%, with $10.2M in open interest and a 1.1% daily increase. OKX follows with 13.0%, or $6.6M, but its OI declined 0.9% over 24 hours and 4.4% over four hours. Gate accounts for 11.9%, or $6.1M, after a 0.9% daily rise.
That split matters. The aggregate increase is being supported by venues such as Bitget and Gate, while OKX is already reducing exposure. Over the shorter four-hour window, all three of these larger books contracted: Bitget fell 0.6%, OKX fell 4.4%, and Gate fell 1.7%. This suggests the latest expansion was not a uniformly sustained build. Instead, new exposure may be arriving at some venues while older positions are being trimmed elsewhere.
Funding is positive, but venue risk differs
Funding remains positive across most of the listed venues, consistent with a long-side bias. Bitget, Gate, OKX and several other venues show rates around 0.0% when rounded to one decimal place, while CoinEx and dYdX are higher at 0.1%. The highest listed rate is dYdX at 0.1%, followed by CoinEx at 0.1%; Kraken is effectively flat at 0.0%.
The broad message is not an extreme funding squeeze. The average eight-hour funding rate is 0.0% after one-decimal rounding, so the cost of holding longs is positive but not broadly elevated. The difference between venues is more informative: traders on dYdX and CoinEx are paying a visibly larger premium than traders on the major books carrying the largest OI shares. If that premium persists while price fails to recover, those pockets can become early sources of forced deleveraging.
Liquidations confirm long-side crowding
The liquidation profile is decisively long-heavy. In the latest 24-hour window, long liquidations reached $243.6K against $55.2K for shorts, out of $298.8K total. The same direction appears in the shorter windows: four-hour long liquidations were $93.3K versus $700.2 for shorts, while the 12-hour figures were $201.3K versus $41.0K.
This is a meaningful confirmation of the price-OI structure. Price has weakened, yet open interest remains higher, and the liquidation burden is falling mainly on longs. That combination often means dip buyers are entering before the market has established support. It also explains why a positive funding backdrop does not automatically equal bullish momentum: longs are paying to stay positioned while already absorbing most of the forced exits.
Verdict
SHIB’s key structure is $0.00000537 price against $50.9M OI: leverage is expanding, but the liquidation map says the immediate pressure remains on longs. The constructive signal would be a recovery that holds above $0.00000537 while OI remains near $50.9M or higher without another acceleration in long liquidations. The bearish view is invalidated if price reclaims that level, long liquidations ease materially from $243.6K, and venue-wide OI continues building without the current four-hour contraction at major exchanges. Data as of 12:15 Beijing time on Sep 20, covering Binance, OKX, Bybit and other major venues.