Solana Derivatives: -21.3% Annual Basis Flags a Fragile Rally
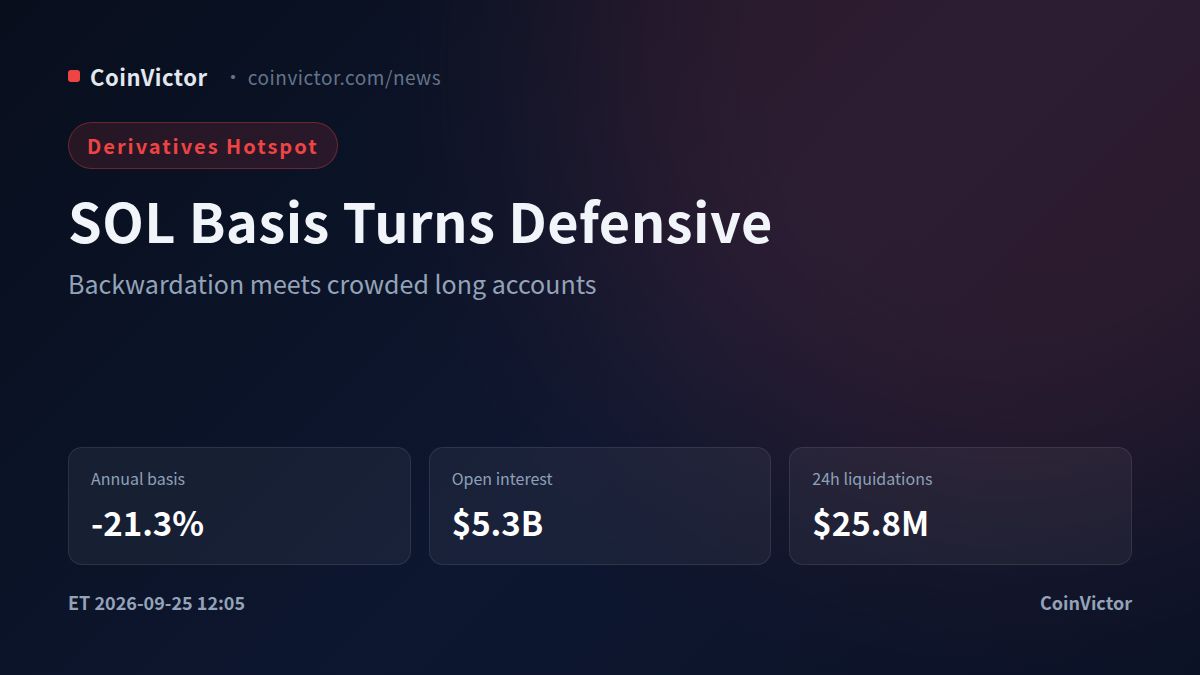
Solana derivatives are sending a split signal at $120.34: total open interest has climbed 6.7% in 24 hours to $5.3B, yet the futures basis is -0.1%, equivalent to -21.3% annualized. That is backwardation, not the usual confirmation of a healthy leveraged upswing. The contrast matters because spot has gained 3.7%, while the derivatives curve still prices contracts below the underlying.
Recent coverage has centered on changes to Solana-related leadership and broader ecosystem developments, but the derivatives tape offers a more immediate test of whether the move can attract durable leverage.
Open interest is expanding unevenly
Among the largest disclosed venues, Binance holds $1.0B of SOL open interest, or 19.0% of the tracked total, after a 5.0% daily increase. Gate follows with $851.3M and a 16.2% share, up 12.4%, while Bybit carries $780.0M, or 14.8%, after the strongest increase of the major group at 14.0%. Bitget adds $476.8M, a 9.1% share, with a more modest 2.4% rise. OKX is smaller at $363.5M and 6.9% of the total, but its 10.2% gain is notable.
The short-term picture is less uniformly bullish. Binance open interest fell 1.5% over the latest four-hour window, Bybit dropped 2.3%, and Bitget declined 0.9%, even as OKX rose 2.3% and Gate increased 0.8%. In other words, daily leverage is still building, but some of the largest books are already reducing exposure into the current price.
Funding is positive on most books, but the curve disagrees
The funding rate distribution is mostly positive: Binance, Bybit, Gate and Bitget each show 0.0% when rounded to one decimal place, while Coinbase and Kraken are also positive at 0.0%. CoinEx is the outlier at -0.6%, although its reported SOL open interest is only $743.1K, or 0.0% of the tracked total. The venue spread therefore does not overturn the broader positioning signal, but it does show that bearish carry has not disappeared everywhere.
The more important message is the mismatch between mildly positive venue funding and a -0.1% aggregate basis. Traders are paying to maintain long exposure on many books, yet the forward contract structure remains defensive. That combination can persist during a spot-led rebound, but it leaves leveraged longs vulnerable if spot momentum stalls.
Positioning looks crowded, while takers are divided
Account positioning is clearly long-biased: 63.9% of tracked accounts are long, against 36.1% short. Bybit is the most stretched among the listed account books, with 68.9% long, while Bitget reaches 74.7%. Binance and OKX are less extreme at 61.6% and 60.3%, and Gate is near balance at 54.1% long.
Active trading is less aligned. Binance takers are 66.6% long, but OKX takers are 54.3% short, leaving Gate almost even at 50.4% long. The aggregate taker split is 50.0% long, materially below the account-long share. That account-versus-flow gap suggests many traders are positioned for upside, while immediate execution is not decisively chasing it.
The liquidation structure reinforces that tension. In the past 24 hours, SOL liquidations totaled $25.8M, including $20.8M of shorts and $5.0M of longs. Over 12 hours, shorts accounted for $17.5M versus $4.2M of longs, but the latest hour flipped slightly toward longs at $673.8K versus $761.0K of shorts. The largest recorded short liquidation was $979.7K at $117.85, followed by $922.7K at $123.02.
Verdict: The base case is a fragile, spot-led rally rather than a confirmed derivatives expansion. The key reference is $120.34 against $5.3B of open interest: a failure back toward the $117.85 liquidation zone would expose crowded longs, while acceptance above $123.02 would force a reassessment. This bearish-backwardation view is invalidated if SOL clears $123.02 and the basis turns positive while open interest holds above $5.3B. Data as of 00:05 Beijing time on Sep 26, covering Binance, OKX, Bybit and other major venues.