Aave Negative Funding Meets $465.9M OI and 61.5% Long Accounts
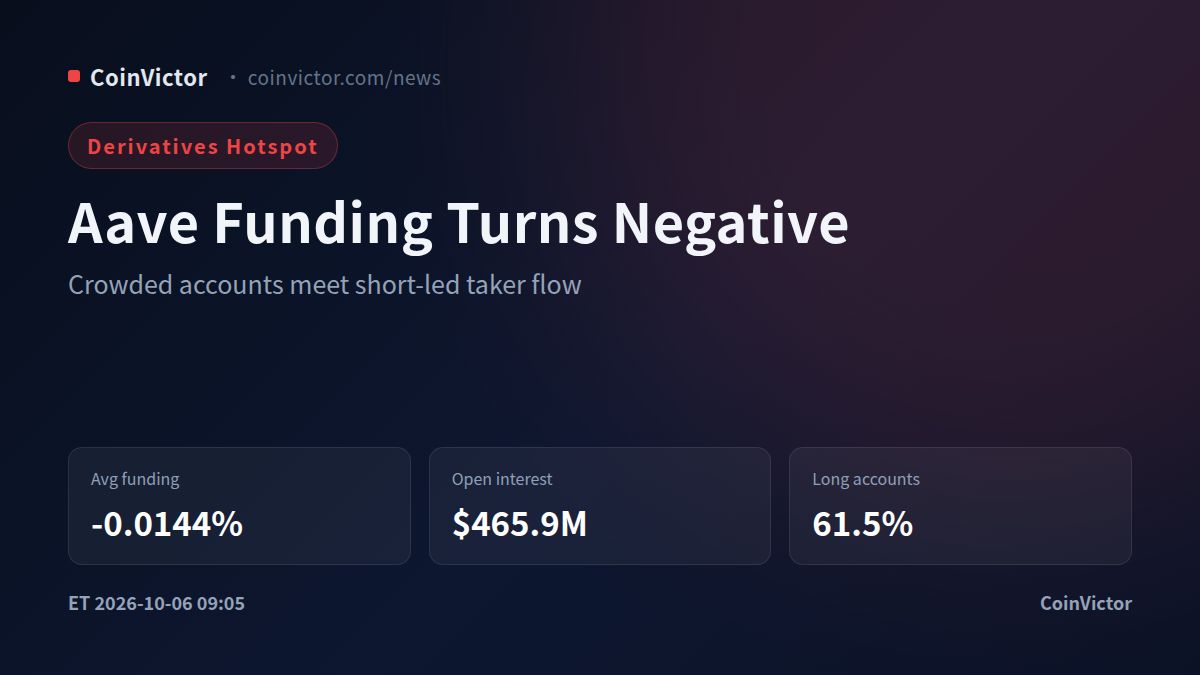
Aave is trading at $184.09 with $465.9M in open interest, but its average 8-hour funding rate has fallen to -0.0144%. That combination matters: leverage remains substantial while the funding burden is now tilted toward longs receiving payment from shorts. The positioning picture is not uniformly bearish, however. Account data shows 61.5% long, while the latest active flow is much more defensive, creating a sharp split between holders and traders actually crossing the spread.
A recent market view also framed the $178 area as a momentum decision zone, but the derivatives data points to a more immediate test around the liquidation clusters at $180.21 and $186.81.
Open interest is rising unevenly
The open interest total is up 1.5% over 24 hours, with the largest venue allocations concentrated on Binance at $87.4M and 18.8% share, Gate at $82.1M and 17.7%, and Bybit at $74.3M and 16.0%. Their changes tell a divided story. Binance OI increased 2.7%, Gate rose 5.8%, while Bybit fell 5.1%. OKX is smaller at $22.6M and 4.9% share, yet its OI jumped 7.7% over the same period.
This is not a clean, broad-based expansion of bullish risk. The biggest growth is appearing at some venues while Bybit sheds exposure, suggesting that the headline OI increase may reflect rotation rather than synchronized conviction. With the market at $184.09, the $180.21 long liquidation level is close enough to remain a downside pressure point if funding stays negative and leveraged longs continue to unwind.
Funding is negative, but not everywhere
The funding-rate distribution is unusually wide. Binance is positive at 0.010%, Gate at 0.010%, Bybit at 0.005545%, and OKX at 0.008744%. In contrast, Bitget is at -0.0104%, Bitfinex at -0.078529%, WhiteBIT at -0.001069%, and CoinEx at -0.429483%. The negative average is therefore being pulled lower by a small group of deeply negative readings, rather than by every major venue charging longs.
That distinction weakens the signal as a simple one-way short call. Negative funding can reflect crowded long liquidation risk, but it can also show that aggressive shorts are paying to maintain exposure on venues where the rate remains positive. The most useful read is the combination of negative aggregate funding, higher OI on Binance and Gate, and falling OI on Bybit: leverage is being redistributed while conviction remains fragmented.
Accounts lean long, takers lean short
The long/short ratio confirms the positioning conflict. Long accounts represent 61.4% on Binance and 63.3% on Bybit, while OKX is 56.0% long. Gate is the exception at 48.3% long and 51.7% short. Active takers are considerably more defensive: Binance takers are only 41.1% long, and Gate takers are 16.2% long against 83.8% short.
Liquidations show why this divergence matters. Over 12 hours, long liquidations reached $122.6K versus $18.6K for shorts, indicating a meaningful long flush. Over 24 hours, the structure nearly reversed into balance, with $274.7K in long liquidations and $321.3K in short liquidations. The largest recorded long events occurred at $181.07 and $180.21, while notable short liquidations printed at $186.14 and $186.81. The market is therefore trapped between a nearby long-stop zone and a higher short-squeeze zone.
Verdict: The near-term bias is negative-to-neutral while AAVE remains below $186.81, because negative average funding, short-led taker flow, and rising OI at Binance and Gate leave crowded long accounts exposed. A break toward $180.21 would strengthen the downside case; the view is invalidated by a sustained move above $186.81 accompanied by OI holding above the current $465.9M level, signaling that upside demand is absorbing shorts rather than merely closing leverage. Data as of 21:05 Beijing time on Oct 6, covering Binance, OKX, Bybit and other major venues.