COTI Gains 4.7% While Kraken Funding Turns Deeply Negative
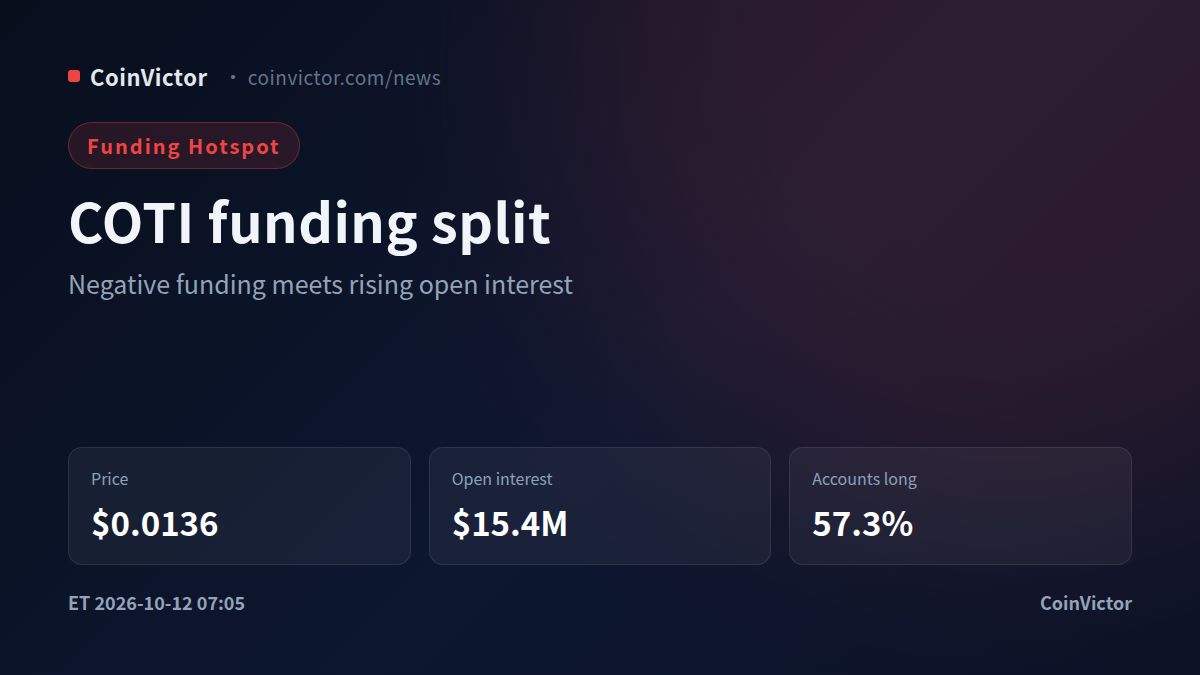
COTI is up 4.7% at $0.0136 while open interest sits at $15.4M, up 2.1% over 24 hours. That combination looks constructive on the surface, but the derivatives signal is more conflicted: the aggregate 8-hour funding average is negative, and Kraken’s rate is a clear outlier at -0.3%. The market is therefore not showing a uniform bearish unwind; it is showing a split funding map underneath a rising-price move.
A recent article presents COTI’s privacy technology as part of a broader payment-focused product direction. That narrative may help explain the positive spot tone, but the derivatives data points to venue-specific positioning rather than a clean, market-wide conviction trade.
OI is concentrated but still expanding
The open-interest structure gives Binance the largest share at 39.9%, with $6.2M deployed and a 0.5% 24-hour increase. Bitget holds 18.4% of OI at $2.8M, up 1.1%, while MEXC accounts for 14.5% at $2.2M after a 4.0% rise. KuCoin is close behind at 14.0%, with $2.2M and the strongest meaningful gain among the larger venues at 7.3%.
This concentration matters because Binance, Bitget, MEXC and KuCoin together dominate the visible positioning. Yet their changes are all positive over 24 hours, so the $15.4M total is not being driven solely by a single exchange. The shorter window is less uniform: Bitget is down 1.4% over 4 hours, Bybit is down 0.8%, and MEXC is down 0.2%, while Binance is up 0.1%. That suggests some recent de-risking inside a broader buildup rather than a full liquidation cascade.
Funding is negative only at the margins
Funding rates do not confirm a broad short-side squeeze. Binance, Bitget, KuCoin, MEXC and several other venues are at positive 0.005%, Bybit is higher at 0.01%, and Crypto.com is also positive. Gate is slightly negative at -0.0012%, but Kraken is the decisive exception at -0.269269%, which rounds to -0.3% under the stated display convention.
The negative aggregate average should therefore be read as a distribution problem. A trader exposed on Kraken is receiving funding from longs at a very different rate from traders on the main positive-rate venues. That makes the headline negative-funding signal useful, but not sufficient evidence that the entire COTI perpetual market is leaning short. It may instead reflect a concentrated imbalance or thinner liquidity at one venue.
Accounts and active flow disagree
The long/short ratio data shows 57.3% of accounts long, but the active taker reading is only 24.8%. That is the clearest directional disagreement in the set. More accounts are positioned long, yet the active-flow measure is far less supportive, implying that the traders crossing the market aggressively are not confirming the majority account bias.
Liquidations add no forced-move confirmation: the 1-hour, 4-hour, 12-hour and 24-hour windows each report $0.00 in long liquidations and $0.00 in short liquidations. With no recorded long-versus-short liquidation imbalance, the negative funding is not being reinforced by a visible flush. The setup is consequently vulnerable to sharp repositioning, but it has not yet produced a liquidation-led trend.
Verdict: The tactical bias is bearish on crowded long exposure, not outright bearish on price. Keep $0.0136 and $15.4M as the key price and OI reference levels: a move below the price level while OI remains near or above the current total would strengthen the negative-funding interpretation, whereas price holding above $0.0136 with OI expanding beyond $15.4M and funding turning broadly positive would invalidate it. Data as of 19:05 Beijing time on Oct 12, covering Binance, OKX, Bybit and other major venues.